
Grupo Emerita Developer: Tulum Portfolio Analysis 2026
Grupo Emerita developer track record, NHOA, Amara, Constelada delivery timeline, financial stability, red flags, and investor due diligence checklist.
By Mexico Invest Editorial · Updated July 9, 2026 · 14 min read
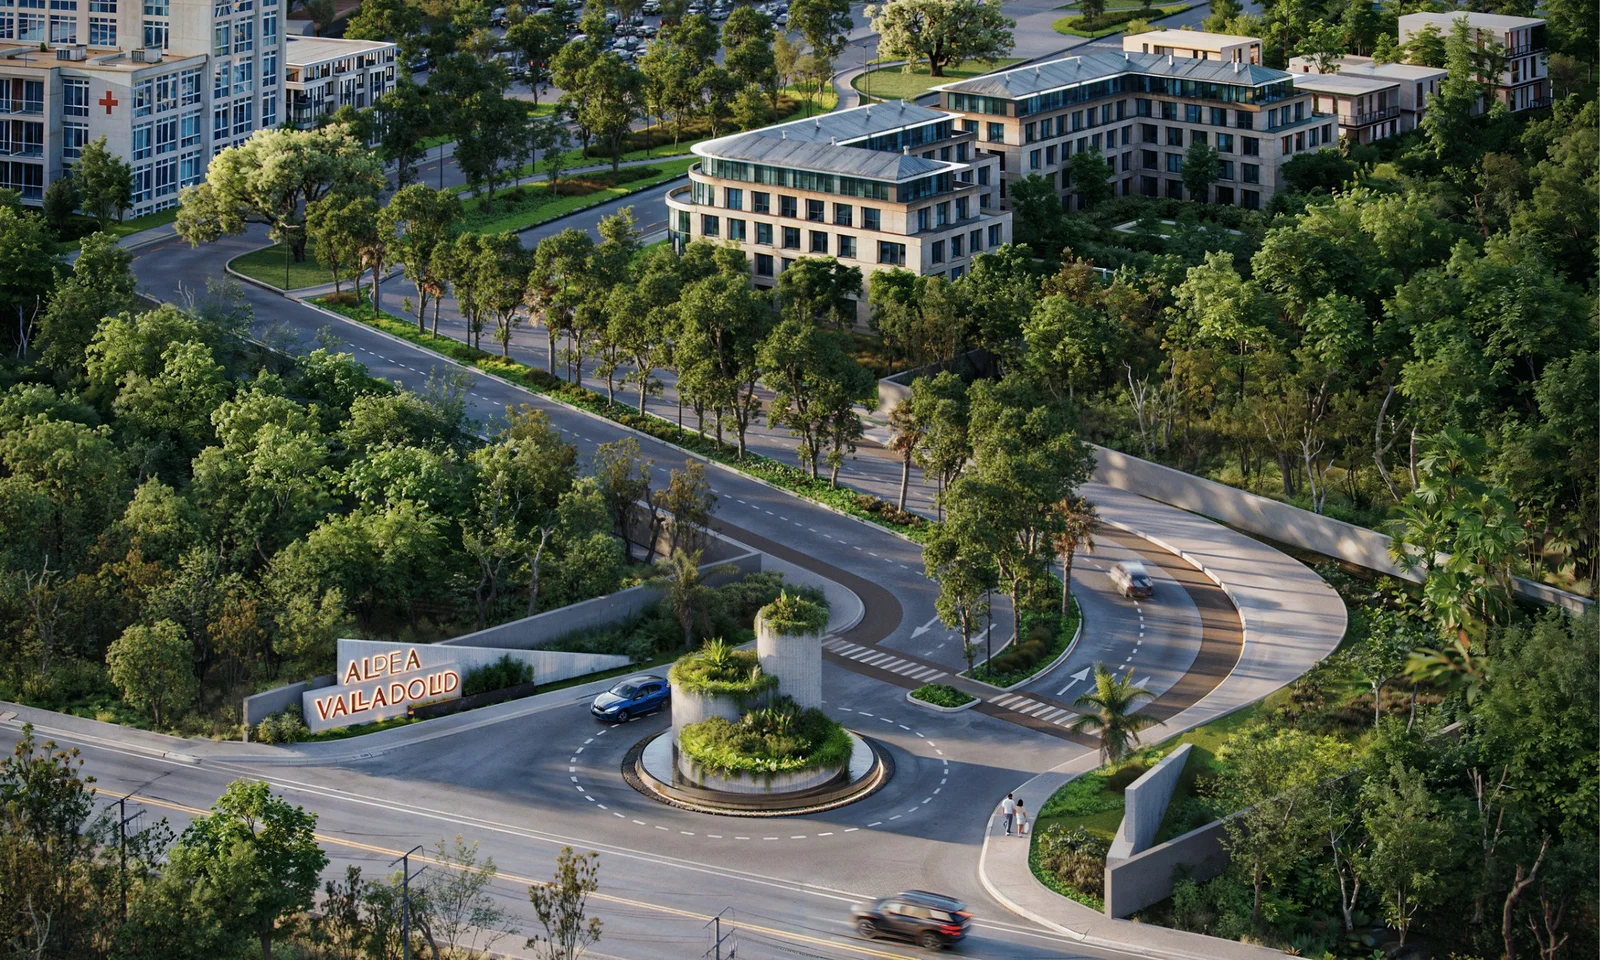
Quick answer: Grupo Emerita operates a multi-project Tulum portfolio, NHOA delivering in Aldea Zama, Amara pre-con in Region 8, plus Constelada, Paravian, and Junglar. Volume suggests Tier-1 status but individual projects require independent permit verification, escrow protection, and zone-specific diligence. No developer brand replaces proper due diligence on licencias, fideicomiso paths, and delivery timelines.
Emerita dominates 2026 Tulum broker conversations through active English marketing and wide price spread ($147K-$510K+) across multiple zones. Volume and marketing sophistication are positive signals, not guarantees.
Developer overview and market position
Grupo Emerita is a volume developer: multiple simultaneous Tulum projects spanning $147,000 to $510,000, English-language marketing and a broker distribution network aimed squarely at foreign buyers. Volume cuts both ways for a purchaser. It implies working capital and repeatable process, which a single-project developer cannot offer, and it means the company’s attention, permits and construction crews are split across sites, so a delay on one project is not independent of the others. Judge the individual project, not the brand.
Grupo Emerita positions as a volume Riviera Maya developer with English-language project marketing, broker distribution network, and multiple simultaneous Tulum developments spanning entry ($147K Amara) to premium ($510K+ Constelada) segments. The company maintains project websites, social media presence, and US-focused sales infrastructure suggesting institutional approach rather than single-project developer typical in Mexican pre-construction.
| Field | Grupo Emerita |
|---|---|
| Market focus | Tulum / Riviera Maya |
| Price range | $147K-$510K+ |
| Status mix | Delivering + pre-con |
| Target buyer | US/Canadian investor |
| Marketing language | English primary |
| Project count | 6+ active (2026) |
Tier-1 volume developer classification based on project count and marketing infrastructure, verify individual project permits independently.
Project portfolio and delivery status
The portfolio splits into what you can inspect and what you have to take on trust. NHOA and phases of Paravian are delivering, so finish quality, real HOA figures and post-delivery administration are all verifiable today. Amara, Constelada and Omara are pre-construction promises. That asymmetry is the most useful thing about buying from a volume developer: the delivered projects are free evidence about the unbuilt ones, and almost no buyer uses them.
Key insight: (NHOA, phases of Paravian) and pre-construction pipeline (Amara, Constelada, Omara). Delivering projects enable operating data diligence; pre-con requires construction timeline and permit verification.
| Project | Zone | Price USD | Status | Unit type |
|---|---|---|---|---|
| NHOA | Aldea Zama | $236K-$280K | Delivering | 2BR lock-off |
| Amara | Region 8 | $147K-$340K | Pre-con | 1-3BR |
| Constelada | Tulum corridor | $169K-$510K | Pre-con | Studio-3BR |
| Paravian | Playa del Carmen (Gonzalo Guerrero) | From $175K | Off-plan | 1BR lock-off |
| Junglar | Riviera Maya | Not yet reviewed | Mixed | n/a |
| Omara | Tulum | Not yet reviewed | Pre-con | n/a |
Key insight: NHOA’s delivering status provides the best evidence of Emerita’s actual finish quality, HOA management, and delivery capability, inspect before evaluating pre-con projects.
How to weigh delivered evidence against pre-construction promises
Read the portfolio in order of proof: completed projects first, delivering second, pre-construction last. Walking NHOA in Tulum, interviewing owners and comparing the marketed HOA against the actual one tells you what Emerita’s promises are worth. What it does not tell you is whether Amara in Region 8 will work, different zone, different timeline, different market conditions, and a pioneer-corridor risk that Aldea Zama simply does not carry.
Critical rule: delivering second, pre-con promises last. NHOA Aldea Zama represents the strongest delivered evidence in 2026, walk units, interview owners, verify HOA performance against pro forma.
| Evidence strength | Projects | Diligence approach |
|---|---|---|
| Strongest | Completed with 12+ mo operations | Owner interviews, resale data |
| Moderate | Delivering (NHOA) | Inspect finish, verify HOA |
| Weakest | Pre-con (Amara, Constelada) | Permits, escrow, timeline only |
Critical rule: Never judge Amara Region 8 pre-con risk by NHOA Aldea Zama delivery, different zones, timelines, and market conditions create independent risk profiles.
Financial stability and corporate structure
Running five projects at once implies reserves that a one-project developer lacks, but Mexican corporate disclosure is thin and the inference is not proof. Ask through your attorney for RFC and corporate registration, financial statements and banking relationships. The warning signs are specific and checkable: a recently formed entity, no prior completions, fire-sale pricing on a sister project, contractor liens, or a refusal to produce corporate documents at all.
Warning signs: to fund multiple projects simultaneously, positive indicator versus one-project developers with limited reserves. However, Mexican corporate transparency is limited; request the following documents in attorney review:
| Document | Purpose | Red flag |
|---|---|---|
| RFC and acta constitutiva | Corporate standing | Inactive status |
| Estados financieros | Balance sheet health | Hidden debt |
| Historial crediticio | Banking relationships | Default history |
| Lista de proyectos | Prior completions | First-time developer |
Warning signs: Recent entity formation, no prior completions, fire-sale pricing on sister projects, contractor liens, or refusal to provide corporate documents.
Developer Due Diligence Mexico, full corporate DD checklist.
Permit verification across Emerita projects
Permits attach to parcels, not to companies, so a clean file at NHOA says nothing about Amara. Verify the licencia de construcción by file number at the Tulum municipio for the specific project, and insist on final SEMARNAT environmental clearance rather than an application in process, cenote discoveries have halted Tulum construction mid-build since 2024, and an environmental stop transfers with the land rather than with the developer.
Tulum-specific risk: volume developer status does not transfer permits between projects. Amara Region 8 needs separate licencia from NHOA Aldea Zama.
| Permit type | Authority | Verify method |
|---|---|---|
| Licencia de construcción | Municipality | File number match |
| Uso de suelo | Municipality | Residential zoning |
| Impacto ambiental | SEMARNAT | Tulum cenote zones |
| Manifestación impacto | State/federal | Construction footprint |
Tulum-specific risk: Environmental stops from cenote discovery have halted projects mid-construction. Verify final environmental clearance, not “in process” applications.
Escrow and payment structure analysis
Milestone payments and escrow are not the same thing: a schedule tells you when money leaves, escrow decides who holds it in between. Verify the arrangement project by project and insist on an independent third-party agent with releases against engineer sign-off; see the escrow guide. “We don’t use escrow, we’re established” is the answer that should end the conversation, at any developer tier.
Never accept: Volume developers sometimes resist independent escrow, insist on 3rd-party agent to protect milestone releases.
| Payment stage | Emerita standard | Investor protection |
|---|---|---|
| Reservation | $5K-$15K | Refundable deposit |
| Contract | 10-15% | Independent escrow |
| Construction milestones | 15-25% each | Engineer sign-off |
| Pre-delivery | 20-30% | Conditional on CO |
Never accept: “We don’t use escrow, we’re established.” Volume does not eliminate escrow discipline.
Escrow Mexico Real Estate, escrow agreement templates.
Zone diversification and concentration risk
Owning two Emerita units in Tulum is one bet made twice. The projects share a developer, a municipality, a supply pipeline and a resale pool, so delivery delays, regulatory changes and price pressure hit both together, and NHOA units competing against newly delivered Amara inventory is Emerita’s own supply pressing on your ADR. Diversify by developer and by market before diversifying by project.
Portfolio strategy: geographic concentration creates correlated delivery risk, supply competition, and resale market correlation. Compare zone-by-zone rather than developer-wide.
| Zone | Emerita projects | Zone risk | Competition |
|---|---|---|---|
| Aldea Zama | NHOA | Lower infrastructure | Multiple developers |
| Region 8 | Amara | Higher pioneer | Emerita + peers |
| Tulum corridor | Constelada | Variable by location | Dense pipeline |
Portfolio strategy: Avoid multiple Emerita projects in same zone, diversify by developer and location for risk reduction.
HOA management and post-delivery administration
Post-delivery administration is where most Mexican developers actually fail, and it is testable in an afternoon: call the NHOA administrator directly and see how fast, how competently and in what language they respond. That single call predicts the service a pre-construction buyer will receive better than any brochure, because the same organisation will be running your building. See HOA fees in Mexican condos for what a well-run one looks like.
Test: inspect Emerita’s administrator competence, reserve fund management, and owner communication. Poor post-delivery administration destroys STR yields regardless of construction quality.
| HOA factor | NHOA example | Red flags |
|---|---|---|
| Monthly assessment | $400-$600 verified | 50%+ above pro forma |
| Reserve fund | Adequate for 5-year capex | Under 10% of budget |
| Delinquency rate | Under 15% target | 30%+ non-payment |
| Communication | Bilingual admin | Spanish-only, unresponsive |
Test: Call NHOA HOA administrator directly, responsiveness and English capability indicate Emerita’s post-delivery service level for pre-con buyers.
Construction quality and finish standards
Inspect delivered units rather than show units, and inspect for the things Riviera Maya humidity attacks: waterproofing first, then plumbing, electrical capacity for air conditioning loads, and common-area maintenance. Then go back at night, noise transfer between units is invisible on a daytime viewing and is one of the most common causes of poor short-term rental reviews in Tulum towers.
Schedule night visit, or completed Paravian phases, inspect plumbing, electrical, waterproofing, and common area maintenance. Mexican construction quality varies dramatically; visual inspection reveals more than marketing renders.
| Quality checkpoint | Inspection focus |
|---|---|
| Plumbing | Water pressure, leak evidence |
| Electrical | Panel quality, outlet functionality |
| Waterproofing | Balcony drains, bathroom seals |
| Doors/windows | Operation, acoustic sealing |
| Common areas | Maintenance, security systems |
Schedule night visit, noise transfer between units affects STR guest reviews.
Emerita against peer developers
Emerita sits in the volume tier: more projects and more delivery history than a boutique operator like SIMCA, less finish-level consistency than a premium brand and no ultra-luxury positioning. Mass-market pricing from $147,000 buys you a company that has built before and quality that varies by project. That variance is the defining characteristic of the tier, and the reason project-level diligence matters more here than developer-level reputation.
Emerita positioning: volume suggests mid-tier institutional but below premium brands with longer track records.
| Developer | Tier | Track record | Price positioning |
|---|---|---|---|
| Premium | Rosewood, OHL | 10+ year | Ultra-luxury |
| Established | SIMCA, Desarrollos | 5+ year | Mid-luxury |
| Volume | Emerita, Mayakoba | 2-5 year | Mass market |
| Emerging | Boutique, first-time | Under 2 year | Variable |
Emerita positioning: Volume tier with multi-project capability, assess project-specific rather than developer-tier assumptions.
What red flags should pause this Mexico purchase?
With a volume developer the useful warning signals are portfolio-wide rather than project-specific: sudden discounting across several projects, a stalled site, contractor disputes, or a pattern of owner complaints about HOA administration. Owner forums and social media from NHOA buyers are a genuinely early indicator, because post-delivery problems surface there months before they appear anywhere official.
Early warning: that could affect project-specific risk, financial stress, regulatory issues, or market positioning changes.
| Red flag | Severity | Action |
|---|---|---|
| Fire-sale pricing on delivered units | High | Investigate distress |
| Contractor liens publicized | High | Pause until resolved |
| Environmental violations | Critical | Stop due diligence |
| Mass broker departures | Medium | Verify sales continuity |
| Permit violations | Critical | Walk away |
| HOA assessment increases over 30% | Medium | Stress test yields |
Early warning: Social media complaints from NHOA owners about HOA issues may predict problems across Emerita portfolio.
What checklist should run before you sign?
Ten checks, all completed before any non-refundable money moves, and all applied to the specific project rather than to Emerita as a company. Familiarity with the brand is the exact circumstance in which buyers skip steps, so treat a comfortable developer relationship as a reason to be more systematic rather than less. See the developer diligence framework for the full version.
Rule:
| # | Item | Status | Responsible party |
|---|---|---|---|
| 1 | Land escritura/fideicomiso | To do | Attorney |
| 2 | Licencia construcción (project-specific) | To do | Municipality verify |
| 3 | Environmental clearance | To do | SEMARNAT file |
| 4 | Developer RFC + financial standing | To do | Attorney |
| 5 | Escrow agreement draft | To do | Independent agent |
| 6 | NHOA inspection (quality reference) | To do | Buyer |
| 7 | Prior buyer references | To do | Broker/attorney |
| 8 | Construction timeline with penalties | To do | Contract review |
| 9 | HOA pro forma vs NHOA actual | To do | Engineer |
| 10 | Zone-specific risks (Region 8/AZ) | To do | Local attorney |
Rule: Complete 10/10 before non-refundable deposit, developer reputation does not replace diligence discipline.
Financing and developer relationships
These are cash purchases in practice. Mexican bank lending to non-residents runs 9-14% against a property yielding under 4%, and no bank lends against an unbuilt unit at all; see the non-resident mortgage guide. Emerita offers developer financing on some projects at premium rates; compare it honestly against a US home-equity draw, which is almost always cheaper and carries no default clause tied to your Mexican title.
Recommendation: foreign mortgages rare at 9-14% rates. Some developments offer developer financing at premium rates; compare to US equity deployment cost.
| Financing option | Terms | Buyer impact |
|---|---|---|
| Cash purchase | Standard | Simplest closing |
| US mortgage cash-out | 4-8% rates | Leverage option |
| Developer financing | 8-12% typically | Higher cost, faster close |
| Mexican bank mortgage | 9-14% rates | Rare for foreigners |
Recommendation: Cash deployment for speed and simplicity, leverage in US market typically cheaper than Mexico developer financing.
Non-resident Mortgage Mexico, financing alternatives.
Resale market and exit strategy
Brand recognition helps a resale; competing against the same brand’s new inventory does not. An NHOA owner selling while Amara delivers is bidding against a developer who can discount and offer incentives that a private seller cannot match. Plan the hold so your exit does not coincide with an Emerita delivery in the same zone, and never list two Emerita units simultaneously.
Exit planning: (supply concentration) for resale. NHOA units competing with new Amara inventory may face ADR pressure.
| Resale factor | Emerita impact |
|---|---|
| Brand recognition | Positive in Tier-1 developer tier |
| Supply competition | Risk from multiple projects |
| Zone concentration | Tulum corridor saturation |
| Buyer pool | US investor focus |
Exit planning: Diversify holding period, avoid simultaneous exits from multiple Emerita properties in same zone.
Investment thesis: when to choose Emerita
| Investor profile | Emerita fit |
|---|---|
| Strong fit | Volume portfolio buyer, comfortable with Tulum zone selection, wants established marketing |
| Moderate fit | Single project buyer seeking mid-tier developer, comparing to SIMCA/peers |
| Weak fit | Premium brand requirement, first-time Mexico buyer, ultra-conservative timeline needs |
Emerita’s value to a buyer is structural rather than reputational: a multi-project pipeline means the company can absorb a problem on one site with cash flow from another, and volume brings marketing reach, established sales infrastructure and a delivery record you can actually check. What it does not bring is uniform quality across projects, Emerita builds in Aldea Zama and in Region 8, and those are very different propositions regardless of the name on the sign. Assess the specific project, its zone and its delivery position rather than the developer brand, and use the fit table below to place yourself.
2026 market positioning and outlook
Emerita’s price range from $147,000 to $510,000 captures several buyer segments at once, which is a real commercial advantage in a competitive Tulum market with active English-language distribution. The corresponding risk is coordination: a pipeline of simultaneous deliveries strains a developer’s capital and crews, and 2026 Tulum is a market where several projects arriving late together would be visible immediately.
Strategic advantage: in competitive 2026 Tulum market. Volume pipeline positions for market share capture but creates delivery coordination risk if multiple projects compete for same labor, permits, or buyer pool.
Strategic advantage: Multiple price points ($147K-$510K) capture different buyer segments within Emerita brand.
Strategic risk: Tulum oversupply particularly in Region 8/15 corridor may affect Amara and Constelada simultaneously.
Riviera Maya Property Investment Guide, market context and trends.
Contract terms and legal review
Budget $2,500-5,000 for independent contract review and closing, around 1% of a $300,000 purchase, and the cheapest protection available. A volume developer’s standard contract is standard for the developer, not for the buyer: delay penalties, delivery specifications, assignment rights and escrow terms are all negotiable, and none of them get negotiated by a buyer who did not read them.
Budget $2,500-$5,000 legal fees volume developer does not mean standardized buyer protection.
| Contract section | Review focus |
|---|---|
| Delivery timeline | Penalty clauses for delays |
| Specification changes | Developer discretion limits |
| Assignment rights | Resale before delivery |
| Force majeure | Environmental/permit stops |
| Default remedies | Refund and termination |
Budget $2,500-$5,000 legal fees for contract review and closing, essential protection on $200K-$500K purchase regardless of developer reputation.
Decision framework: Emerita project selection
Within the portfolio, the ranking follows risk tolerance directly: a first Mexican purchase belongs in delivering inventory where everything is verifiable, and pre-construction in a developing corridor is a deliberate speculative allocation rather than a default. Whichever project you choose, the three non-negotiables are the same, independent attorney, independent escrow, verified permits.
Universal rule:
| Risk tolerance | Project recommendation |
|---|---|
| Conservative | NHOA delivering (inspect first) |
| Moderate | Constelada pre-con (verify permits) |
| Aggressive | Amara Region 8 (zone pioneer) |
Universal rule: No Emerita project without independent attorney, escrow protection, and permit verification, brand does not replace diligence discipline.
Final assessment
Grupo Emerita operates as a volume Tier-1 developer with multi-project Tulum portfolio spanning $147K-$510K across delivering and pre-construction inventory. NHOA’s delivering status provides quality reference point; individual project DD remains mandatory for permits, escrow, and zone-specific risks. Volume and English marketing suggest institutional capability, not guarantee of delivery performance or yield outcomes.
Verify all permits and contracts with independent counsel. Mexico Invest is editorial only.
Frequently Asked Questions
Grupo Emerita operates multiple Tulum/Riviera Maya projects including NHOA (delivering), Amara, Constelada, Paravian, and Junglar with English marketing and broker distribution. Volume suggests Tier-1 status but does not replace permit verification, escrow requirements, and project-specific due diligence.
Emerita's delivering/completed inventory includes NHOA in Aldea Zama and phases of Paravian and Junglar. Pre-construction pipeline adds Amara Region 8, Constelada corridor, and Omara. Verify specific tower completion dates and inspect finished product before evaluating developer quality.
NHOA Aldea Zama shows delivering status in 2026. Pre-con projects like Amara target mid-2026 delivery, standard 6-18 month delays are common industry-wide. Contract penalty clauses and milestone escrow protect against developer delays better than track record assumptions.
Emerita marketing suggests milestone payments but verify escrow structure project-specific. Independent escrow with 3rd party agent protects better than developer trust accounts, require written escrow agreement before any deposit over 10% purchase price.
Emerita spans $147K entry (Amara) to $510K+ premium (Constelada) with NHOA at $236K-$280K delivering. Volume developer strategy covers multiple price segments, assess zone and unit type rather than developer brand alone.
Portfolio concentration risk, multiple Emerita projects may correlate in delivery delays, market cycles, and resale demand. Diversify across developers, zones, and delivery timelines rather than betting on single developer brand.
Emerita volume exceeds boutique developers but trails established brands like SIMCA (101 Park). Compare project-specific permits, delivery history, and financial stability rather than marketing materials, each development carries independent risk.
Get a vetted Mexico shortlist
US and Canadian buyers use this to skip the developer sales deck: tell us the budget and the market, and we come back with 3 to 5 options and the net yield maths behind each one.
Want options matched to your budget and risk profile?
Three questions, one screen. We reply within one business day.
Get a vetted Mexico shortlist